You have six SIPs running. You started them at different times, for reasons you no longer remember. There is a term plan somewhere that a colleague sold you in 2019. Your EPF balance is a number you have never actually looked at.
You earn well, but you have no structure to your finances. So you searched for the term “financial planning process,” hoping for a clear answer.
In this article, you will understand what financial planning is and learn about the steps of a financial plan.
You will get a step-by-step DIY financial planning process, along with free Indian tools most people have never heard of. And you will find out when you should hire a financial advisor and how to tell a good financial advisor from a salesperson.
So let’s get started.
What Is the Financial Planning Process?
The financial planning process is a step-by-step method used to plan your finances in such a way that your financial goals and life goals are actually met.
Without a proper financial plan, you still end up investing, but you invest without any direction behind it. The money goes wherever it was last suggested to you. The result is a set of investments spread across places that are not giving you the returns you assumed. None of them were set up to account for the way your life changes.
Because your life does change. Your salary rises, you get promoted, you switch jobs, or you lose one. A child arrives and your expenses double. Yet the investments you started five years ago carry on exactly as they were, as though none of it had happened.
A financial plan fixes that by giving you a clear picture of what needs to change to suit the life you are actually living now. It tells you which of your existing investments are doing their job and which are simply sitting there. It also shows what has to be added or removed so that each of your goals is properly funded.
Having a proper financial plan in place also gives you a far better handle on your expenses. You know what you can comfortably spend, what has to be set aside every month, and what you are setting it aside for. That clarity is what a sound financial life is built on.
Objectives of Personal Financial Planning
People assume the objective of financial planning is “higher returns.” It is not.
The real objectives of financial planning are simpler and far more useful:
- Know where you stand financially. Most people do not understand their current financial situation. Knowing where you stand financially is the first important step in financial planning.
- Build Tangible Financial Targets. Build financial goals that are tangible. “Buy a house someday” is a wish. ₹50 lakh down payment by March 2031″ is a financial goal.
- Adequate Funds. One of the important goals of financial planning is to have adequate funds to fulfill your life goals, like emergency medical expenses, a child’s higher education and marriage, and your retirement plan
- Liquidity. Most Indian households have the majority of funds in gold jewelry and real estate. A good financial plan should also account for cash flow so that emergency expenses can be met.
- Simplicity and Clarity. A good financial plan should be easy to follow and also to update as the years progress.
Notice that none of these say “beat the market.”
This is where most disappointment starts. If you walk in expecting a stock tip, you will walk out unhappy, no matter how good the plan helps you.
Quick Check: Write down what you want your financial planning to do for you. If your answer is only “make more money,” reset that expectation before you spend a rupee on financial planning.
The 6 Steps of the Financial Planning Process
Before you go further, one thing worth saying early. The right first move is never a product, it is a plan. A great mutual fund bought in the wrong order can still leave you short of an emergency fund, or paying tax you did not need to. Proper financial planning sorts the order out first, so every rupee you invest is actually pulling towards something you want.
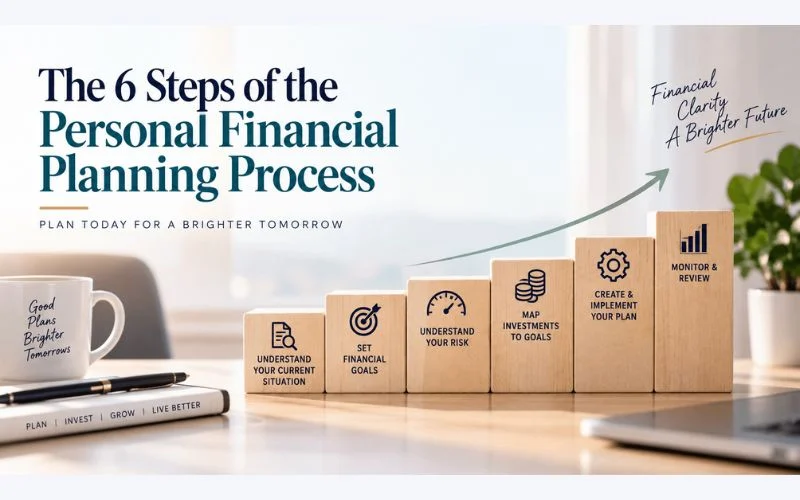
Step 1: Understand your current financial situation
You cannot create a financial plan without knowing where you are standing.
This step in the financial planning is simply a full inventory. What you own, what you owe, what comes in, and what goes out.
What you own: bank balances, fixed deposits, mutual funds, shares, EPF, PPF, NPS, gold, property, and insurance policies with a maturity value.
What you owe: home loan, car loan, personal loan, credit card outstanding, and any money borrowed from family.
What flows:your monthly income and your actual expenses. Not what you think you spend. What you actually spend.
Subtract what you owe from what you own. That number is your net worth. It is the single most useful number in your financial life, and most people have never calculated it.
My financial framework splits expenses into three buckets, which makes this far easier:
- Investment expenses (your SIPs and savings, treated as a bill you pay yourself)
- Annual expenses (insurance premiums, school fees, festival spending, travel)
- Regular expenses (rent, groceries, utilities, EMIs)
Most people only track the third bucket. Then the second bucket hits in March or at year-end, disrupts the month, and affects the next 2-3 months.
Quick Note: In India, this step is harder than it sounds. Very few families have a complete picture of their current financial situation. Give yourself a weekend for this, not an hour.
Step 2: Set clear financial goals
Setting financial goals without a number and a date is just a wish.
Every goal needs three things attached to it:
- What it is (your child’s college education)
- When you need it (June 2038)
- What it will cost then, not today
That last point is where most people go wrong. Education costs in India have been rising far faster than general inflation. A course that costs ₹20 lakh today will not cost ₹20 lakh in 2038.
Here is a starting list of goals by life stage:
| Life stage | Typical goals |
|---|---|
| Unmarried, working | Emergency fund, health cover, first home, higher studies |
| Newly married | Home purchase, joint emergency fund, life cover, car |
| With young children | School fees, higher education corpus, bigger home, retirement |
| With working children | Retirement income, children’s marriage, parents’ healthcare, estate planning |
Not every goal is the same kind of goal
Before you decide where money goes, sort each goal into one of three types. This one habit prevents most short-term money mistakes.
| Type | What it is for | When you need it | Examples |
|---|---|---|---|
| Emergency fund | The unexpected | Could be tomorrow | Job loss, medical emergency, urgent repair |
| Sinking fund | Known expenses you can see coming | Within 1 to 3 years, often yearly | Insurance, school fees, festivals, a planned trip |
| Medium to Long-term Financial goal | Big one-off targets | 3 years or more away | Home down payment, child’s college, retirement |
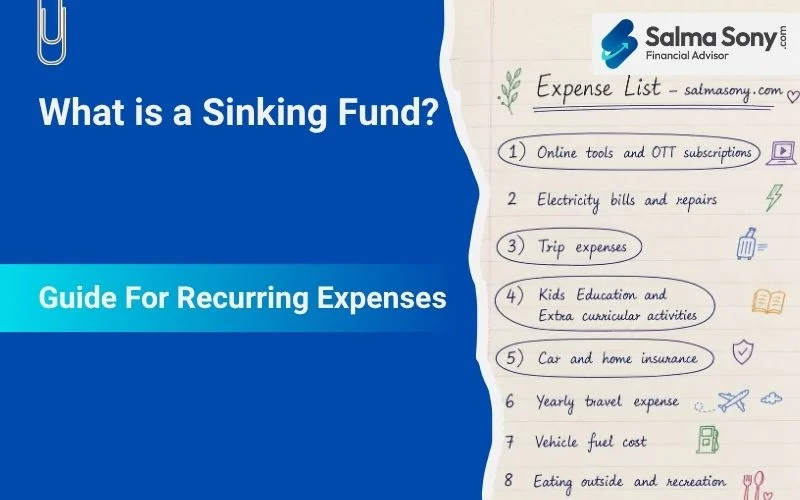
The middle one is the one almost everybody misses. A sinking fund is money set aside for a known expense that is coming, usually every year.
Take Ananya, a 33-year-old consultant in Hyderabad. Her car insurance of ₹18,000 arrives once a year and wrecks that month every single time. It should not. She now puts ₹1,500 aside monthly, and the money is simply there when the renewal lands.
These expenses feel like surprises. They are not. You knew about every one of them twelve months in advance.
Look back at the three expense buckets from Step 1. That middle bucket, your annual expenses, is your sinking fund list already written out. You just have not funded it yet.
Quick Check: List every expense you paid last year that was not monthly. Insurance, school fees, festivals, travel, car servicing. Add them up and divide by 12. That number is what your sinking fund needs each month.
Read More About It Here: What is a Sinking Fund?
One more move happens here that almost nobody does on their own. A financial planner expands your list, then ranks it.
Take Meera, a 36-year-old marketing manager in Pune. She arrived with three goals: a bigger flat, her son’s education, and retirement. Her adviser added two she had not mentioned, adequate health cover and a will, then ranked all five. Health cover went first. The flat dropped to fourth.
That reordering and adequate funding is the real work of building a stable financial future. Not the fund selection.
Step 3: Understand your risk appetite
Before anyone decides where your money goes, they need to know how much of a fall you can survive.
This risk management is done through a short questionnaire. It asks about your age, how long until you need the money, how stable your income is, how many people depend on you, and what you would do if your investments dropped 20% in three months.
Your answers produce a risk profile. That profile then decides how your money splits between equity (higher risk, chances of higher long-term return) and debt (lower risk, lower return).
Sounds mechanical. It is not, and the next section explains exactly why.
Note: Higher risk does not guarantee higher return; it just increases the chance of making a higher return in the long run. Hence, investing based on your risk appetite and goal is essential.
Step 4: Map different investments to your financial goals
This is goal-based investment planning, and it is the heart of the whole process.
The rule is simple. Match the investment to the timeline of the goal, not to your mood.
| When you need the money | Where it usually belongs |
|---|---|
| Emergency fund (any time) | Savings account and liquid funds only |
| Under 3 years (sinking funds) | Fixed deposits, recurring deposits, arbitrage fund, liquid funds |
| 3 to 7 years | A mix, leaning conservative |
| Over 7 years | Mostly equity funds with a debt mix (60:40 or 70:30), based on risk profile |
Sinking fund money should never go into equity. You will need it in eleven months and hence should be invested in instruments where you can redeem it after that exact time period.
This split is called asset allocation. Think of it as choosing the vehicle for each journey. A short city trip needs something different from a cross-country drive.
Two other things get fixed at this step.
Insurance, sized properly. Not less, not more, but adequately covered. Term life cover if anyone depends on your income. Health cover for the whole family, separate from your employer’s policy, because that policy ends the day your job does.
Debt. I frequently tell my clients, “When it is an EMI, you are making the bank rich. When it is a SIP, you are working for your own wealth.” Clear the expensive loans first, then convert that EMI amount into an investment.
Step 5: Create a Financial Plan
A financial plan you have not acted on is just a document.
Implementation is the unglamorous part. Forms, KYC, bank mandates, nominee updates, surrendering the policies that are not working for you.
A few things that make it stick:
- Automate everything. Set your SIP date for the day after your salary lands, not the end of the month. Allocate a separate bank account for this.
- Update nominees everywhere. Bank accounts, mutual funds, EPF, insurance. A ten-minute job that saves your family months.
- Do it in priority order. Insurance and emergency fund first, investments after.
One honest warning about what you receive. Some financial advisers hand over a hundred-page report. Others send five pages and a phone call. A detailed plan will be a long document, but there must be a summary for quick reference. Ask what the deliverable looks like before you sign anything.
Step 6: Monitoring and review
Life does not follow your spreadsheet.
Review your financial plan at least once a year. Also review it whenever something big happens: a baby, a job change, a job loss, an inheritance, a property sale, a move abroad, or a death in the family.
What you check each time:
- Are you still on track for each goal, or has the cost changed?
- Has your asset allocation drifted because equity ran up?
- Has your income changed enough to increase your investments?
- Is your insurance still adequate for your current liabilities?
This is also where a financial adviser saves your finances in a way you notice only later. One investor described how his adviser stopped him from panic-selling everything in March 2020. Another was steered out of a debt fund before it froze. Neither shows up in a returns table.
Financial Planning Process : A Real Example
Here is what the whole process looks like applied to one family.
Meet Meera (36) and Karthik (38), both working in Pune, with a five-year-old son. Combined take-home is ₹2,40,000 a month.
Step 1: Where they stand
| What they own | Amount |
|---|---|
| Savings account | ₹3,50,000 |
| EPF (both) | ₹16,00,000 |
| Mutual funds (6 SIPs, ₹30,000 a month) | ₹19,00,000 |
| Karthik’s company shares | ₹24,00,000 |
| Flat | ₹85,00,000 |
| Home loan outstanding | minus ₹46,00,000 |
| Net worth | ₹1,01,50,000 |
Monthly expenses are ₹1,35,000, including a ₹48,000 EMI. Annual expenses come to ₹2,88,000, which is ₹24,000 a month they have never set aside. Surplus: ₹81,000 a month.
Step 2: What they want
Emergency fund of ₹8,10,000 (six months of expenses). A sinking fund of ₹24,000 a month. Their son’s education in 2039, costing ₹35 lakh today, which becomes roughly ₹1.21 crore by then at 10% education inflation. And retirement at 58, which is 22 years away.
Step 3: What the analysis found
Four problems they had not seen:
- The emergency fund is short by ₹4,60,000
- Nearly 40% of their investable money sits in Karthik’s employer’s stock. His salary and his savings depend on the same company
- Karthik has only ₹40 lakh of life cover, all through his employer. He needs closer to ₹2 crore
- Six SIPs, holding largely the same stocks. That is duplication, not diversification
Step 4: Risk and allocation
Their capacity for risk is high, with 22 years to retirement and two stable incomes. Their tolerance is moderate. Their goals need about 11% a year. Allocation was set separately for each goal, not as one blended number.
Step 5: What they actually did
| Action | Monthly cost |
|---|---|
| Top up emergency fund over 8 months | ₹57,000 (temporary) |
| Start the sinking fund in a separate recurring deposit | ₹24,000 |
| Term cover: ₹2 crore for Karthik, ₹1 crore for Meera | ₹3,200 |
| Independent family health cover of ₹25 lakh | ₹2,800 |
| Education SIP to reach ₹1.21 crore in 13 years | ₹35,000 |
| Sell 60% of the company shares over 3 years, move into diversified funds | (from existing assets) |
| Consolidate 6 SIPs into 3 | (no extra cost, if planned well) |
The first eight months are tight. After the emergency fund is full, that ₹57,000 shifts to retirement.
Step 6: What happens next
One review every February. One rule: if anything major changes, they call before making a decision.
Notice what did not happen. Nobody found them a secret fund. The whole gain came from ordering, sizing, and removing a risk they could not see.
Risk Profiling: Why Two People With the Same Salary Get Different Portfolios
An investor once shared that his adviser “went through the process of risk assessment,” classified him as a moderate investor, and based his equity-to-debt allocation on that assessment. He thought it was box-ticking.
It was actually the most important thing in his plan.
Risk profiling measures three different things, and most people collapse them into one.
| What it measures | What it means | How it is judged |
|---|---|---|
| Risk capacity | How much loss you can financially survive | Facts: timeline, income stability, dependants, emergency fund, insurance |
| Risk tolerance | How much loss you can emotionally handle | Behaviour: what you actually do when markets fall |
| Risk required | How much risk your goals actually demand | Maths: the return needed to hit your targets |
These three often disagree. That disagreement is the whole conversation.
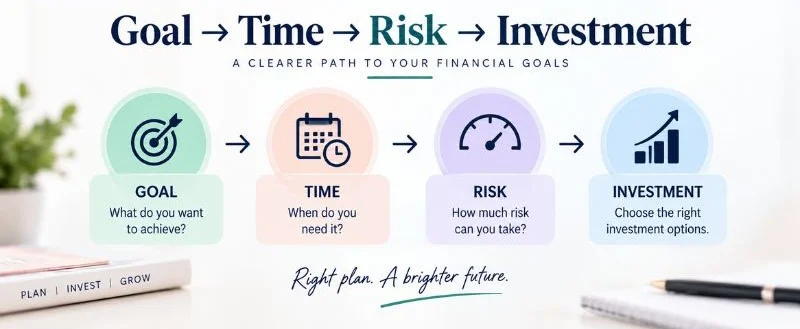
Take Rahul, 34, an IT professional in Bengaluru with a stable income and no dependants. His capacity is high, with thirty years to recover from anything. His tolerance is low, because he sold everything in a correction two years ago. And his expectation is 11% a year, so his required risk is high too.
No questionnaire solves that. A financial planner has to sit with him and help him to spend less, work longer, or learn to sit still through a fall.
This is not just my view. The CFP Board’s own standard lists “capacity for risk” as objective information and “risk tolerance” as subjective information. Two different categories, in the profession’s own rulebook.
“I am young, so I can take more risk.”
This is the most common sentence in Indian personal finance. It is only half true.
Being young does give you time, and time genuinely raises your risk capacity. You have decades to recover from a fall, so a bad year matters far less.
But look at the capacity row in that table again. Time is only one of the inputs. It also asks about your emergency fund, your insurance, and how stable your income is.
So a 28-year-old with no emergency fund and no health cover does not have high capacity. He has plenty of time and very little capacity.
What does that mean in practice? The moment something goes wrong, a hospital bill, a job loss, or a family emergency at home, he has to sell his investments to pay for it. Usually at the worst possible moment, because emergencies do not wait for markets to recover.
Age only starts working in your favor once the fundamentals are in place. In this order:
- An emergency fund covering three to six months of expenses
- Adequate health cover for you and your family, separate from your employer’s policy
- Term life cover, if anyone depends on your income
Get those three done, and your age becomes a genuine advantage. Skip them, and being young simply means you have more years of exposure to the first thing that goes wrong.
You do not know your risk tolerance yet
There is a second half to that sentence, and almost nobody mentions it.
If you started investing recently, you have not been tested. You have watched your portfolio go up. You have not sat through the months where it does not, wondering whether to stop your SIP.
A questionnaire cannot tell you how you will behave. Only a real fall can.
And this matters more than it sounds, because one bad early experience can permanently change how someone thinks about money. Plenty of people who lost money in 2008 have never bought equity again, seventeen years later.
That is not irrational. It is what happens when someone takes more risk than they had actually agreed to and then finds out during the fall.
So if you are just starting, begin below your capacity, not at it. Let yourself live through a real correction with an amount you can watch calmly. Then increase once you know how you actually respond.
Quick Check: Ask yourself what you did in early 2020, or in the correction after that. If you cannot remember, or you were not invested, treat your risk tolerance as unproven and start conservative.
Two more things worth knowing.
Allocation is set per goal, not per person. Your two-year car fund and your twenty-five-year retirement money should not sit in the same place, whatever score you got.
Your profile is not permanent. A questionnaire filled in during a bull run will overstate your tolerance. People who called themselves aggressive in 2021 found out otherwise the following year. Re-check it after you have actually lived through a fall, because that answer is the real one.
What Do You Actually Get in a Financial Planning Process by a CFP?
If the above six steps are done properly, the deliverable writes itself. It should contain your current position, your goals with costs and dates, the gap between them, your asset allocation, insurance recommendations, a tax view, and an action list with deadlines.
What varies wildly is the format. Ask about it upfront.
But here is the part that catches people out. A good financial plan often looks boring.
Two Indian investors wrote about this within a year of each other. One said the plan he paid for was “nothing extraordinary,” mostly fixed deposits for short-term goals and two or three mutual funds for the long ones. He added later, “I guess I was expecting some hidden instruments that will give amazing returns.”
There are no hidden instruments.
Think of it like going to a doctor with a bad cold. If she tells you to rest and drink water, you feel short-changed. If she prescribes three medicines you did not need, you feel looked after. The first answer was the correct one.
The same trap runs in reverse. Another investor worried whether advisers deliberately build complicated portfolios so clients feel they got their money’s worth. Too simple feels cheap. Too complex feels like theatre.
Which is why the expectation has to be set before you pay, not after.
Importance of Financial Planning
The importance of financial planning is easy to assert and harder to prove. So here is the evidence.
Vanguard, which manages trillions of dollars, studied what the planning process itself is worth. Its research put the value of the discipline, mainly the tax and allocation decisions, at as much as 1.5% of extra return per year. Morningstar’s separate study found 1.8% in improved portfolio efficiency.
So what does that mean for you? On a ₹1 crore portfolio, 1.5% is ₹1.5 lakh a year. Compounded over twenty years, that is not a rounding error.
But the returns are not the whole story, and often not even the main story.
One investor summed up what he actually bought for ₹12,000: “I now have peace of mind. I am just happy that I can stop reading all those articles and looking for videos from a thousand different YouTubers.”
Another had been refused health insurance by every private insurer because of a pre-existing condition. His adviser told him to visit a public insurer’s branch manager in person and explain the situation. He got the policy issued, with no increase in premium. That is not portfolio management. That is knowing how the system works.
A financial planner in a family works like a family doctor. Not someone you call in a crisis, someone who checks on you regularly so the crisis does not arrive.
How the Financial Planning Process Changes for Your Situation
The six steps stay the same. What changes is where the pressure sits.
Salaried professionals
Your EPF and/or NPS are already a large chunk of your retirement money, and most people never count them. Check the balance before deciding you have saved nothing.
If your part of CTC also includes shares, watch the concentration. Vikram, a 41-year-old in an MNC, had 58% of his net worth in one employer’s stock. His salary and his savings depended on the same company.
And stop treating tax planning as a March activity. Decisions made in March are almost always worse than decisions made in April.
Dual-income couples
Two salaries, and still no money at the end of the month. This is more common than you would think.
The problem is usually that neither of you has a joint plan. Two sets of investments, two policies, and no agreement on whose goals get funded first.
Settle this early: your child’s education or your retirement? There is a hard truth Indian parents rarely hear. Your children can borrow for college. You cannot borrow for retirement, so never give low priority to your retirement funding.
Business owners and self-employed
Irregular income means your emergency fund needs to be bigger, not smaller. Aim for nine to twelve months of expenses instead of the usual three to six.
You also have no employer safety net. No group health cover, no EPF, no automatic retirement contribution. You are now responsible for all of that.
Keep business money separate from personal money. Mixing them makes both harder to plan.
NRIs
Your residency status changes the plan before any investment does. Where you are a tax resident decides what gets taxed where, and getting that wrong is expensive.
Kunal, 38, works in Singapore and has been sending money to India for eight years. His plan looks nothing like his Bengaluru cousin’s, even though they earn similar amounts.
If a return to India is on the horizon, start planning two to three years out. There are tax advantages available in your first years back that disappear if you miss them.
One thing to know upfront: advisers usually quote NRIs more. Cross-border work involves two tax systems, India’s foreign exchange rules, and treaty positions, which genuinely takes longer.
HNIs with scattered investments
If you have investments across a dozen platforms, your first problem is not returns. It is that you cannot see the whole picture.
Overlap is the usual finding. Twelve mutual funds holding the same twenty large-cap stocks is not diversification; it is expensive duplication. However, you can’t eliminate it, but you can reduce it.
This is also the group most likely to need a will, and least likely to have one.
DIY Financial Planning: Can You Do This Yourself?
Yes. For a lot of people, genuinely yes.
If your situation is straightforward, you have a few hours, and you will actually stay disciplined, you can achieve your financial goals on your own.
DIY works well when: you have one or two income sources, your goals are more than five years away, no property transaction is pending, and there is no cross-border element.
DIY usually breaks at: marriage, a baby, buying a house, a windfall, starting a business, moving abroad or returning, and the five years before retirement.
Step by step DIY financial planning
Here, financial planning is the same six-step process, reorganized for one person doing it alone.
- Pull all your data into one place. Every account, policy, loan, and investment. The hardest step, and the most valuable.
- Write every goal with a number and a year. Inflate the cost forward. Do not use today’s price.
- Sort each goal into emergency fund, sinking fund, or long-term goal.
- Calculate your net worth and monthly surplus.
- Fix the three foundations before investing anything. Emergency fund, term cover, health cover.
- Decide your allocation goal by goal, using the timeline table above.
- Automate it, then schedule one annual review.
The 50/30/20 rule helps here. Roughly 50% of take-home to needs (including EMIs), 30% to wants, 20% to savings and investments. A starting point, not a law.
Also Read: Financial Plan: How To Plan Personal Finance Better in 2026?
Financial planning tools you must know about
Most articles recommend American apps that do not work in India. Here are the ones that do, starting with free official sources almost nobody uses.
Consolidated Account Statement (CAS) from CAMS. Every mutual fund and share you own, across every fund house, in one PDF. If you have six SIPs you cannot account for, this is where you find them.
MF Central. A joint portal from CAMS and KFintech giving a consolidated view of your mutual funds, free.
Your AIS on the income tax portal.The Annual Information Statement shows interest, dividends, and large transactions the tax department already knows about. The fastest way to find forgotten accounts.
EPFO passbook or the UMANG app. Your actual provident fund balance.
Your free annual credit report from any credit bureau.
The SEBI adviser registry. Verify anyone before you pay them.
A spreadsheet. Still the honest answer for goal maths, because you control the assumptions.
Portfolio trackers like Kuvera, ET Money or INDmoney are useful for tracking. Most are free because they earn from the products they recommend. Use them to see, not to decide.
Quick Check: Download your CAS this week. It takes five minutes, and almost everyone finds something they had forgotten. I have surprised many clients in their first year of sign-up with mutual funds they had forgotten.
Do You Need a Fee-Only Financial Advisor in India, and How to Choose Someone?
Before this gets into cost, one point worth repeating. The first move is a plan, not a product. Buying a good fund before you have an emergency fund, adequate insurance, and a clear goal is how people end up with strong investments and a weak financial life. That ordering is exactly what good financial planning services sort out first.
What a financial plan actually costs
The current fee limit under Fixed Fee mode is Rs 1,51,000/- per annum per family of clients.
Almost nobody publishes this in India. Here are real ranges investors have reported.
| What you get | Typical cost |
|---|---|
| First-year comprehensive plan | ₹12,000 to ₹1.51 lakhs |
| Yearly retainer after that | ₹5,000 to ₹1.51 lakhs |
| NRI or cross-border engagement | Higher, often ₹45,000 to ₹1.5 lakhs |
One investor put the fee in perspective usefully. He pointed out that ₹18,000 buys roughly one hour of a mid-level partner’s time at a law firm. For a financial plan, it buys several hours of work plus a year of access.
There is no minimum wealth requirement, whatever you may have read. The question is not how much you have. It is whether your decisions are complicated enough that getting them wrong would cost more than the fee.
How financial advisers get paid in India
This matters more than any qualification, because it quietly shapes the advice you receive.
| Model | Who pays them | The risk to you |
|---|---|---|
| Commission | The product company | They earn more by selling certain products |
| Percentage of Assets under Advice (AUA)* | You, as a % of your portfolio | They earn more as your portfolio grows |
| Flat fee (fee-only) | You, directly | None built in. The fee is the same whatever they recommend |
A fee-only financial advisor in India charges you directly and earns nothing from the products they suggest. That removes the conflict the other two models carry.
One adviser explained the three models as a drive from Mumbai to Bangalore:
A wealth manager says: Give me your car; I will drive, and you give me a share of what you make.
Most advisers say: You drive; I will sit beside you and tell you when to change lanes.
A fee-only adviser says: Tell me where you want to go and why; here is your route. I am not in the car, but call me if you get lost.
Quick Note: Anyone charging a fee for investment advice in India must be registered with SEBI, the market regulator. Someone who only sells you mutual funds is a distributor, not an adviser. They are paid by the fund house, and the fund house charges you.
The cost of getting this wrong is real. One investor described how his 50-year-old father, with no finance background, was put into small-cap funds by a commission-earning salesperson. Four years later, that ₹50 lakh investment was still behind inflation.
Also Read: The Crucial Role of Financial Planning
Five questions to ask before you hire a financial advisor
- Are you registered with SEBI, and what is your registration number? Then check it on the SEBI website yourself.
- How exactly are you paid, and by whom? If any part of the answer involves a product company, you know what to watch for.
- What will I actually receive at the end, and how long will it take?
- How many meetings do I get, and how do I reach you between them?
- What happens in year two, and what does it cost?
Practical Takeaways
Do this today. Write down every goal, with two numbers beside it: what it costs in today’s money, and the year you will need it. Ten minutes.
Do this today. List every SIP you are running, with the fund name and monthly amount. Flag any you cannot remember starting.
Do this this week. Download your Consolidated Account Statement from CAMS.
Do this this week. Add up every non-monthly expense from last year and divide by 12. That is your sinking fund contribution.
Do this this month. Check whether you have a valid, registered will. If you have children under 18 and no will, that is the most urgent gap to achieve financial freedom, and it has nothing to do with returns.
The Bottom Line
The financial planning process is not complicated. Six steps: know where you stand, decide where you are going, understand how much risk you can carry, match your money to your timelines, actually do it, and check in every year.
What makes it feel complicated is that nobody explains it the same way twice.
If you are just starting out, do it yourself. Use the DIY steps and the free tools above. You will understand your financial needs far better for having done it.
If something big is happening (a baby, a house, a business, a move abroad, or retirement within five years), that is when a second pair of eyes pays for itself.
If your investments are scattered everywhere and you have no idea whether they are working, start with the CAS download. You cannot plan what you cannot see.
Whichever applies, the first step is not choosing a fund. It is seeing your goals, your risk, your timeline, and your tax position together, before the calendar decides for you. That is exactly what financial planning services are built to do, help you achieve financial stability in your life.
FAQs: Financial Planning Process
Q-1: What are the 6 steps of the financial planning process?
Understand your current financial position, set clear goals with amounts and dates, understand your risk appetite, map investments to each goal, implement the plan, and review it at least once a year. This is the six-element process used by FPSB, the global standards body that financial planners are trained on.
Q-2: What is a sinking fund, and how is it different from an emergency fund?
A sinking fund is for expenses you know are coming, like insurance renewals, school fees or festivals. An emergency fund is for things you cannot predict, like a job loss or a medical crisis. Keep them in separate accounts, or you will spend the emergency money on a wedding gift.
Q-3: What is the 50/30/20 rule of money?
A simple budgeting guide. Roughly 50% of your take-home pay to needs like rent, groceries and EMIs. About 30% to wants. The remaining 20% to savings and investments. Adjust it to your own situation.
Q-4: Can I do financial planning myself?
Yes, and many people should. If your income is straightforward, your goals are years away, and you will stay consistent, the DIY steps here will get you most of the way. It gets harder around big life events, or once you have money in more than one country.
Q-5: How much money do I need before hiring a financial adviser?
There is no minimum, despite what you may read. The better question is whether a mistake would cost you more than the fee. A ₹25,000 fee that prevents one bad ₹5 lakh decision has already paid for itself.
Q-6: What is the difference between a financial planner and a mutual fund distributor?
A distributor sells you products and is paid by the fund house. An adviser registered with SEBI is paid by you and must act in your interest. They look identical from outside. Ask how they are paid, and the difference becomes obvious.
Q-7: Is a fee-only financial adviser better?
Fee-only means they earn nothing from the products they recommend, so there is no built-in reason to prefer one fund over another. It does not automatically make someone good at their job. It removes one common source of bad advice.
Q-8: How often should I review my financial plan?
At least once a year. Also review it any time something significant happens: marriage, a baby, a job change, a job loss, an inheritance, a property sale, or a move abroad. Life events matter more than calendar dates.
Q-9: My adviser only suggested fixed deposits and two mutual funds. Was I cheated?
Mostly not. Good financial advice is often unexciting, especially if your situation is uncomplicated. There are no secret investments that generate high returns at low risk.
Q-10: Is financial planning just maths?
Why do I need a person? The maths is the easy half. The CFP Board’s own standard lists values, attitudes, expectations and family circumstances as required inputs, alongside the numbers. Choosing between your child’s education and your own retirement is not an arithmetic problem.